Florida Property Tax Reform | Updated November 9, 2026
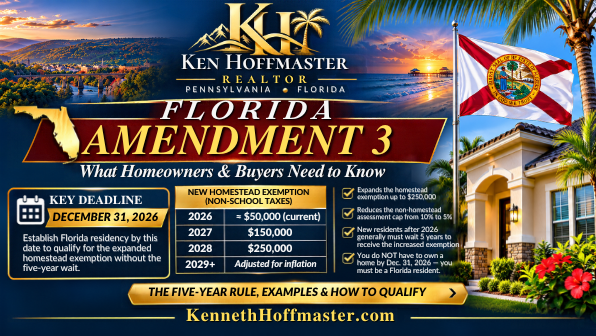
Florida voters have approved Amendment 3. The biggest headline is a much larger homestead exemption—but the detail that may matter most to relocating homeowners is a December 31, 2026 residency cutoff and a new fifth-year eligibility rule for people who become Florida residents in 2027 or later.
The short version
Amendment 3 takes effect January 1, 2027. For qualified homeowners, the non-school homestead exemption becomes up to $150,000 in 2027 and $250,000 in 2028, with inflation adjustments beginning in 2029. Residents who establish permanent Florida residency after December 31, 2026 generally receive the smaller initial benefit until their fifth year of homestead exemption. That five-year period does not restart every five years.
Analysis by Kenneth Hoffmaster, REALTOR®Florida & Pennsylvania

What did Florida voters approve?
In the November 3, 2026 general election, Florida voters approved Amendment 3 with approximately 62% voting yes—above the 60% required for a constitutional amendment. Those returns are still identified as unofficial pending certification as of this publication. The measure amends Florida’s Constitution in four main areas: the homestead exemption, assessment increases on non-homestead property, certain residency rules, and the permitted uses of county and municipal property tax revenue.
It is not a repeal of all property taxes. It does not remove school district property taxes, HOA dues, insurance premiums, special assessments or other costs of ownership.
2026 vs. 2027 vs. 2028: the homestead changes
A homestead exemption reduces the taxable assessed value of a qualifying person’s permanent primary residence; it does not subtract a cash amount directly from the tax bill. Florida’s 2026 homestead exemption is worth up to $51,411 for non-school levies: the first $25,000, plus an inflation-adjusted additional $26,411. The first $25,000 also applies to school levies. Amendment 3 replaces that non-school structure with a much larger total non-school exemption for eligible owners.
| Tax year | Non-school homestead exemption | School taxes |
|---|---|---|
| 2026 | Up to $51,411 under existing law | $25,000 exemption |
| 2027 | Up to $150,000 for eligible owners | $25,000 exemption remains |
| 2028 | Up to $250,000 for eligible owners | $25,000 exemption remains |
| 2029+ | Inflation-adjusted exemption; future expansion may require legislation | $25,000 exemption remains, barring other law changes |
Important: $150,000 and $250,000 are amounts of assessed value exempt from certain property taxes, not refunds and not guaranteed savings of those dollar amounts. A property cannot exempt more assessed value than it has. Counties and municipalities may also receive authority, through implementing legislation, to increase exemptions further under defined procedures.
December 31, 2026: why the date matters
The amendment draws a dividing line based on whether someone is a permanent Florida resident on December 31, 2026. Under guidance published by the Leon County Property Appraiser:
- Already a Florida resident by that date: you may qualify for the expanded exemption when you own and properly homestead a qualifying Florida primary residence, subject to constitutional and administrative requirements.
- A Florida resident by that date, but not yet a homeowner: the cutoff concerns genuine residency; you do not have to complete a home purchase by December 31, 2026 merely to preserve eligibility for the larger exemption on a later qualified homestead.
- Not a permanent Florida resident until January 1, 2027 or later: the amendment provides a smaller initial non-school exemption and generally delays the expanded exemption until the fifth year of homestead exemption.
Changing the address on a document alone does not create Florida domicile. Genuine permanent residency depends on the actual facts, including where you live and intend to make your permanent home. You should not claim conflicting homestead or principal-residence benefits across states. County property appraisers administer homestead determinations; new statewide implementation details may further clarify documentation.
Does the five-year clock ever reset?
No, there is no automatic five-year reset cycle in Amendment 3. For people who move to Florida in 2027 or later, it establishes an initial waiting period. The larger exemption begins on January 1 of the fifth year of exemption, following four years with a Florida homestead exemption, as Leon County’s property appraiser currently explains. It does not mean you must repeat five years over and over.
Illustrative timeline: first homestead exemption in 2027
2027 — Year 1, smaller exemption
2028 — Year 2
2029 — Year 3
2030 — Year 4
2031 — Year 5: expanded exemption begins, if eligible
If the first homestead year is 2028, the fifth year would ordinarily be 2032. That distinction matters: the operative example is based on years of homestead exemption, not merely five calendar years after driving into Florida. Moving or buying a new property may introduce other administrative questions, particularly for continuity of exemption; obtain written guidance from the county property appraiser rather than assume a transfer will preserve every condition.
The ballot text also includes a qualifier—“to the extent permitted by the U.S. Constitution”—so constitutional questions and implementation may affect the final application of the new-resident distinction. The Legislature is expected to provide additional procedures.
How much money might a homeowner save?
Savings depend on the home’s assessed value after any Save Our Homes limitation, the owner’s eligibility, other exemptions, and the non-school millage rate. One mill equals $1 in tax per $1,000 of taxable value. For an eligible established resident with enough taxable assessed value to use the full increased exemption, these illustrative figures compare the expanded exemption with 2026’s $51,411 non-school baseline. They are not quotes or predictions of actual tax bills.
| Illustrative non-school millage | 2027 reduction | 2028 reduction |
|---|---|---|
| 5 mills | ~$493/year | ~$993/year |
| 10 mills | ~$986/year | ~$1,986/year |
| 15 mills | ~$1,479/year | ~$2,979/year |
Example method: (new maximum non-school exemption minus 2026’s $51,411 baseline) × hypothetical millage ÷ 1,000. Assumes sufficient assessed value, the same millage and assessment, no other exemptions and full eligibility. Real bills may differ materially.
A $200,000 assessed-value home may have all of its non-school taxable value covered by the 2028 exemption, but it can still owe school taxes and charges not based on taxable assessed value. Conversely, an established owner with a low taxable assessed value might already pay little non-school ad valorem tax, limiting any savings.
What about school taxes, Save Our Homes and portability?
The larger homestead exemption applies to non-school property taxes. Florida school district taxes remain, with the $25,000 homestead exemption continuing to apply to school levies. The amendment also does not repeal Save Our Homes, the separate provision generally limiting annual assessed-value growth on homesteaded properties to the lower of 3% or CPI. Existing portability provisions are not changed by Amendment 3. Nor does the measure itself repeal additional exemptions for qualifying veterans, seniors or surviving spouses.

How does Amendment 3 affect rentals, second homes and commercial property?
These properties generally do not qualify for the increased homestead exemption. Instead, Amendment 3 lowers the annual cap on increases in assessed value for qualifying non-homestead property from 10% to 5% for non-school levies, starting in 2027. This can slow increases in tax-assessed value for second homes, rental homes and commercial real estate.
That is not a 5% property tax cap, not a 5% reduction in taxes and not a cap on market prices. The change does not necessarily prevent reassessment when ownership or use changes, and school-tax values are calculated separately. Investors should have the county confirm the property’s assessment status and should model taxes based on their own acquisition rather than the seller’s current bill.
What is the potential impact on local government and services?
There is a real tradeoff. Lower taxable values help qualifying property owners, but they also reduce revenue at unchanged tax rates. Florida TaxWatch, using state Revenue Estimating Conference figures, estimates lower local property tax collections of about $4.93 billion in fiscal 2027–28, rising to $8.71 billion in fiscal 2028–29. Those are statewide projections, not a promised cut to any one department or household.
Supporters argue homeowners need relief from rising assessments and local governments should prioritize core functions. Critics and some local officials warn that reduced revenue may pressure emergency services, infrastructure and community programs, or encourage changes in millage, fees or spending. Both the level of relief and the budget response will vary by municipality and county.
The amendment also limits stated uses of county and municipal property tax revenue to categories including public safety, education and schools, infrastructure, natural resources, bond debt service, employee retirement benefits and operations/administration, while allowing certain other expenditures with appropriate local approval unless restricted by law. Nothing in that list guarantees a particular funding level for police, fire or rescue services.
Practical checklist for buyers and homeowners
- Determine whether you were a permanent Florida resident by December 31, 2026. Keep legitimate supporting documentation; do not rely on a last-minute paperwork change unsupported by actual domicile.
- Verify homestead eligibility for your specific property. A second home or rental is not a primary-residence homestead simply because you own it.
- Apply through your county property appraiser. Homestead generally depends on owning and occupying the permanent residence as of January 1 of the tax year, with a March 1 filing deadline; county-specific forms and permitted late-filing provisions should be checked.
- Review your assessed value, not only listing price. Save Our Homes, portability and reassessment on a purchase can make tax outcomes very different for neighboring properties.
- Separate school and non-school millages. Only non-school levies receive the increased exemption.
- Read the August 2027 TRIM notice and November 2027 bill. Those are the first routine notices expected to reflect the amendment for qualified property owners.
- Ask the property appraiser about individual situations. Transfers, partial ownership, trusts, multi-owner homes, residency continuity and mixed personal/rental use deserve case-specific answers.
Answers to common questions
Do I need to buy a Florida home before December 31, 2026?
No—not merely to qualify for the existing-resident side of the cutoff. Leon County expressly states that a person who establishes permanent Florida residency by December 31, 2026 may be eligible for the larger exemption after a later qualifying home purchase. Owning and qualifying for homestead are separate requirements.
Does the five-year period start over at the end of year five?
No. The fifth year marks the first year of the expanded exemption for otherwise eligible new residents; it is not a repeating five-year renewal cycle.
Does living in Florida for five years without owning a home count?
The published Leon County guidance frames the wait as the fifth year of homestead exemption for people whose permanent residency begins in 2027 or later. Do not assume years of residency alone substitute for maintaining a qualifying homestead exemption.
Does it eliminate the entire property tax bill?
No. School taxes remain, as can non-ad valorem assessments and fees. Some low-assessed-value qualifying homes may see no taxable assessed value for non-school levies.
Will every new Florida buyer get $250,000 off in 2028?
No. The 2028 amount is the maximum non-school assessed-value exemption for eligible homeowners, and the five-year rule may delay expanded benefits for new permanent residents.
What happens if local governments increase the millage rate?
A lower taxable value can be partly offset by a higher tax rate. Actual bills depend on assessed values, all applicable millages, fees and future implementing law.
What should we watch next?
Amendment 3 takes effect January 1, 2027, but county property appraisers are awaiting implementation guidance on certain details. The Florida Legislature is expected to address uniform procedures, administrative questions and any additional authorized increases. The status of the five-year provision also carries an express federal constitutional qualifier. Property owners should rely on updated official county and state guidance as it becomes available—not viral social posts that promise a fixed tax refund or an automatic loophole.
Official and research links
- Leon County Property Appraiser: Amendment 3 FAQ and implementation updates
- Florida Election Watch: Amendment 3 statewide voting returns (unofficial as of November 9)
- St. Johns County: amendment summary and legislative documents
- Florida TaxWatch: statewide and county-level property tax impact resources
- Florida Legislature’s Office of Economic and Demographic Research: revenue estimating conference
- Duval County Property Appraiser: homestead eligibility and filing examples
Considering a move to Florida—or reviewing the tax impact before buying?
A good real estate decision begins with verified facts. I help buyers and sellers in Florida and Pennsylvania evaluate their next move, including questions to take to the appropriate county property appraiser.
Prepared by Kenneth Hoffmaster, REALTOR®. Florida brokerage: Jason Mitchell Real Estate Florida LLC. Educational information, not legal or tax advice. This article reflects public information available November 9, 2026. Actual eligibility and tax bills are determined by the applicable county offices and law.